Slab Leak Insurance Help in Bryan, TX
Navigating property insurance claims after discovering water under your foundation requires objective, comprehensive technical documentation. We supply the diagnostic reports, moisture mapping, and photo evidence your adjuster needs.
Call (888) 205-7875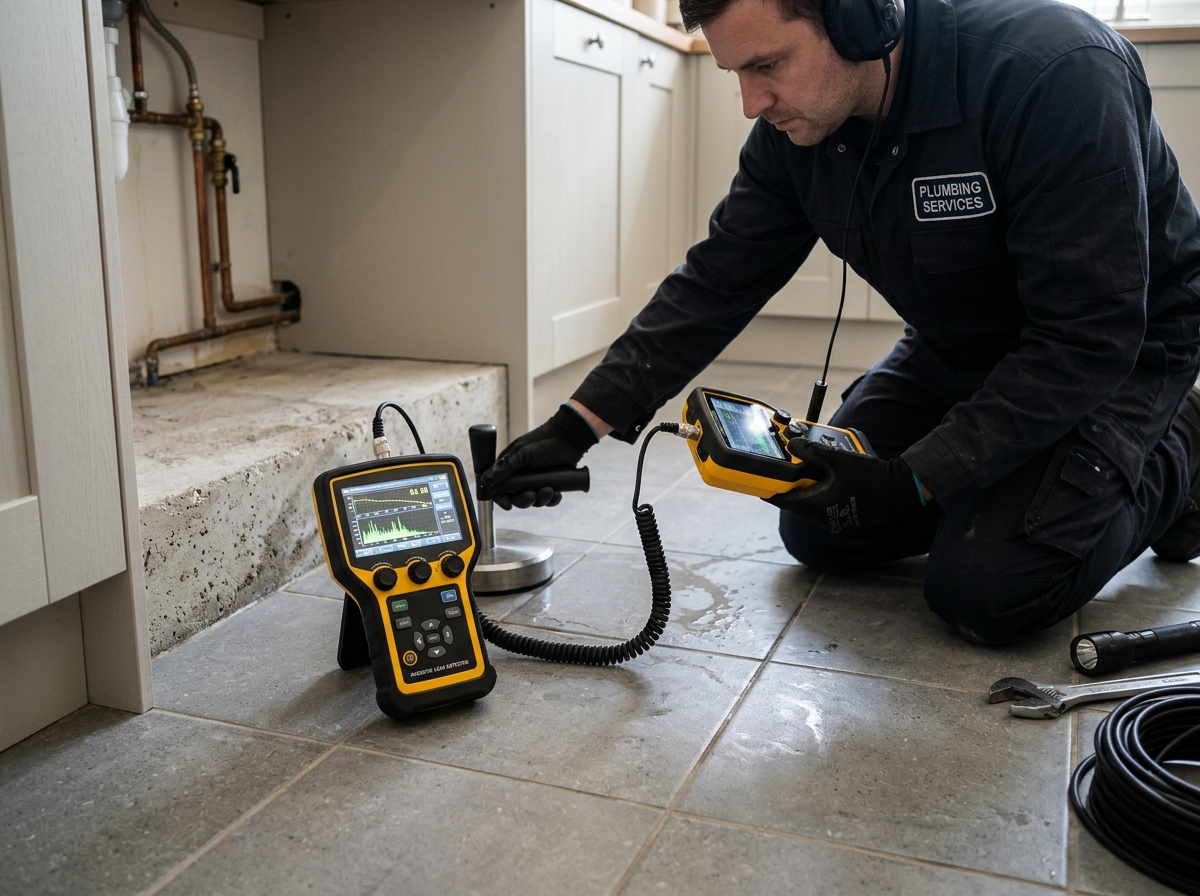
Understanding Homeowners Insurance and Slab Leaks in Texas
Discovering a subterranean plumbing failure is an overwhelming experience for any homeowner. One of the first questions property owners ask is: does homeowners insurance cover slab leaks Bryan residents encounter? The answer depends heavily on your specific homeowner policy endorsements, policy language, and the nature of the damage. While our technicians provide plumbing expertise and technical documentation—not legal or licensed insurance advice—understanding common policy structures helps you navigate discussions with your claims adjuster.
In standard Texas residential homeowner policies (such as HO-B or HO-A with water endorsements), insurance coverage is typically divided into three distinct operational categories: the physical pipe repair, tear-out or access costs, and resulting water damage. Before contacting your insurance carrier, arranging professional slab leak repair in Bryan diagnostics ensures you have verifiable evidence.
The Three Parts of a Foundation Leak Claim
Insurance policies frequently treat the physical components of a foundation leak claim differently:
- 1. The Pipe Repair Itself: In many standard policies, the plumbing pipe itself is considered a normal wear-and-tear home maintenance item. The direct cost of replacing the cracked copper fitting or pipe segment is often excluded or subject to strict limitations.
- 2. Access & Tear-Out Coverage: This is frequently the most substantial financial component of a claim. Many Texas policies provide coverage for the cost of "tearing out" and accessing the portion of the foundation or building required to reach the damaged pipe, as well as the cost of patching the foundation concrete back to its pre-loss condition.
- 3. Consequential Water Damage: Water damage caused by sudden, accidental discharge—such as saturated drywall, ruined carpets, buckled hardwood flooring, warped cabinets, or baseboard damage—is commonly covered under comprehensive water damage endorsements.
Why Thorough Technical Documentation Is Crucial
When you file a slab leak insurance claim Bryan insurance adjusters require objective, third-party technical evidence before approving tear-out and restoration estimates. Incomplete or ambiguous invoices frequently result in claim delays or denials. Our technical documentation packet provides comprehensive evidentiary proof:
- Written Leak Detection Summary: A signed, detailed technical statement confirming system static pressure before and after isolation, verifying that an active, pressurized breach was detected.
- Exact Coordinate Mapping: Detailed diagrams identifying the precise subterranean location, depth, and orientation of the failing pipe relative to foundation beams.
- Thermal Imaging & Acoustic Decibel Logs: High-resolution thermographic imagery showing heat signatures radiating through the slab and acoustic frequency readings documenting escaping water.
- Moisture Mapping & High-Resolution Photos: Clear photographic evidence of floor dampness, warped materials, efflorescence, and water meter movement. This professional slab leak documentation Bryan adjusters rely upon streamlines claim processing.
Immediate Steps Homeowners Should Take
If you suspect an active foundation leak, follow these immediate procedural steps:
- Mitigate Further Damage: Shut off the main water valve if water is pooling inside the home. Insurance policies require property owners to take reasonable steps to prevent continuous consequential damage.
- Preserve Evidence: Do not immediately discard damaged rugs, flooring samples, or drywall pieces. Photograph everything thoroughly in place before cleanup.
- Call for Professional Detection First: Obtaining a verifiable diagnostic report before an adjuster visits ensures you have clear evidence demonstrating that an active, covered subterranean leak exists.
- Review Your Policy Endorsements: Read your declarations page carefully and contact your insurance agent or carrier to review your specific water damage, slab access, and foundation endorsements.